
Making Room for Co-Living
17 September 2026
Homeownership has long been the cornerstone of Singapore's housing model, with nine in 10 resident households owning the homes they live in. Against this backdrop, the emergence of a viable housing format built on shorter leases would have been less obvious a decade ago. Yet co-living has grown rapidly over the past five years, evolving from a niche accommodation concept into an increasingly visible segment of the country's housing landscape.
The potential of this demand was amplified when construction delays and border disruptions hit during the pandemic. The reopening further fuelled a rapid recovery in international mobility and rental market conditions tightened as demand rose across multiple tenant groups.
Between 2022 and 2023, URA’s private residential rental index spiked sharply, which at its peak, had risen by over 40%. Direct acquisitions of co-living assets climbed as operators sought to scale their portfolios, while a number of transactions for operating platforms, such as Mitsubishi Estate’s buyout of Habyt, also emerged. Although deal volumes softened in 2025 amid a tightening supply of investable assets, conversion opportunities have revived activity this year. In August 2026, CapitaLand Ascott Trust’s proposed S$134 million acquisition and leaseback of the 212-room Coliwoo Midtown offered a further sign of the sector’s growing institutional appeal.
Investments Pick Up in 2026
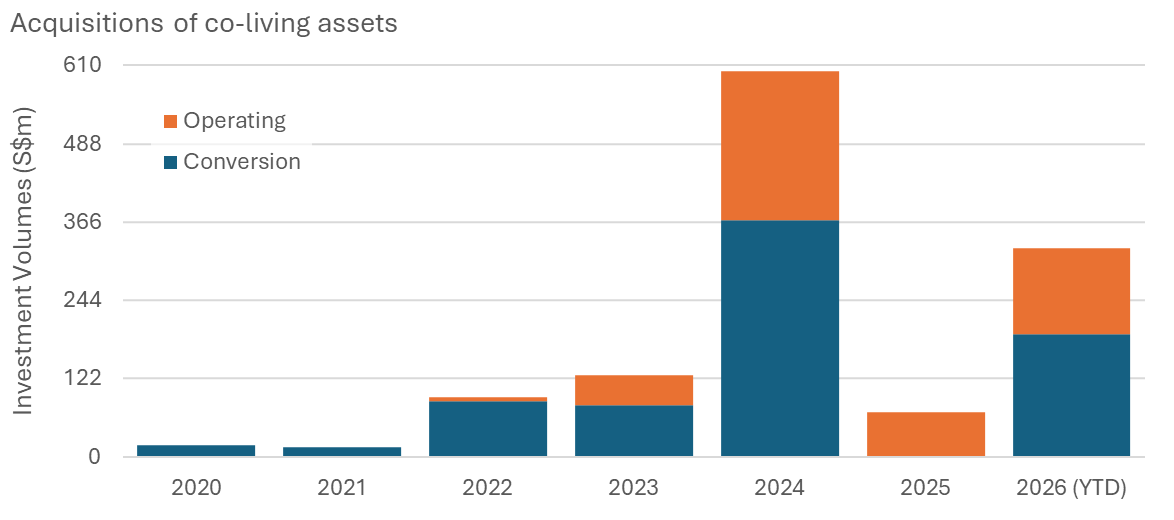 Note: inclusive of properties bought for conversion
Source: MSCI, Knight Frank Research
More Reasons to Rent
Expectations of a recalibration in co-living demand post-pandemic have evidently been premature. The sector has continued to expand even after rental market conditions began to normalise, suggesting that demand was supported by longer-term structural drivers rather than a temporary spurt. While the surge in rental costs has made the sector more viable, its durability evidently extends beyond operating margins.
Several factors have expanded the demand for flexible housing solutions in Singapore. International student enrolments continued to grow, while Singapore's international workforce has remained sizable, with more than 200,000 Employment Pass holders.
The demand base is also broadening beyond the traditional expatriate and student segments. A growing number of local residents are choosing to rent during different life stages, whether waiting for a new home to be completed, be closer to workplaces or to gain greater independence.
Changing Household Formation
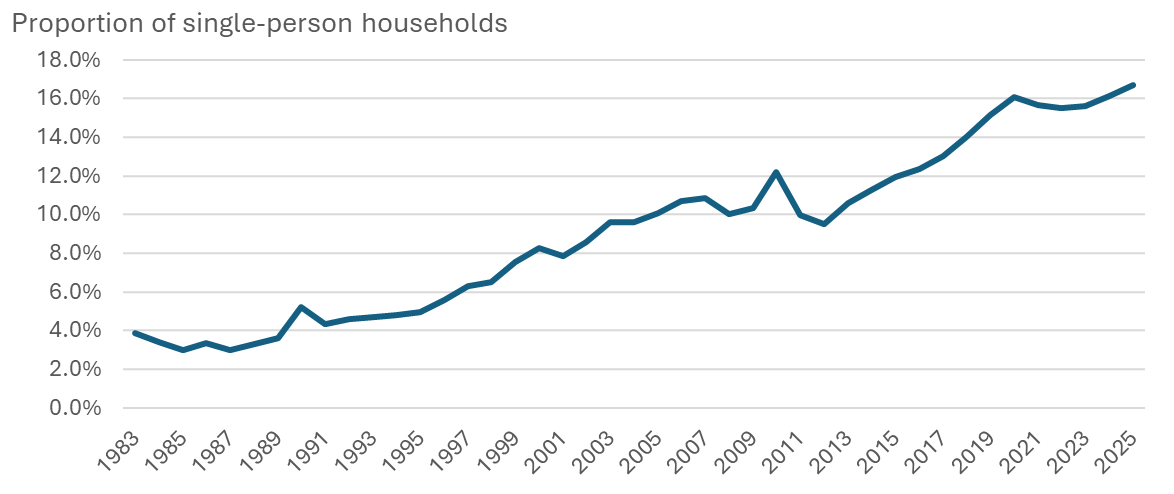
Source: Singstats
At the same time, trends in household formation have shifted. Single-person households now account for nearly one in six resident households. Notably, much of the rise recorded between 1980 and 2015 was repeated in just the last decade. As more people choose to live alone, demand for smaller and more flexible housing options is likely to increase. In this respect, co-living makes sense as the presence of a community and ready amenities can make compact living more appealing.
With the demand profile of renters becoming increasingly diverse, a rental stock predominantly made up of housing developed for ownership is unlikely to be an optimal solution. An estimated 9,000 to 10,000 co-living keys are now operating across the island, while sustained investment interest points to its growing presence within Singapore’s housing market.