Making room for co-living in Singapore as sector comes of age
17 September 2026
Homeownership has long been the cornerstone of Singapore’s housing model, with nine in 10 resident households owning the homes they live in. Against this backdrop, the emergence of a viable housing format built around shorter leases might have seemed unlikely a decade ago.
Yet co-living has grown rapidly over the past five years, evolving from a niche accommodation concept into an increasingly visible part of the country’s housing landscape.
The potential for such demand became more apparent when construction delays and border disruptions hit during the pandemic. The reopening of borders then fuelled a rapid recovery in international mobility, while rental market conditions tightened as demand rose across multiple tenant groups.
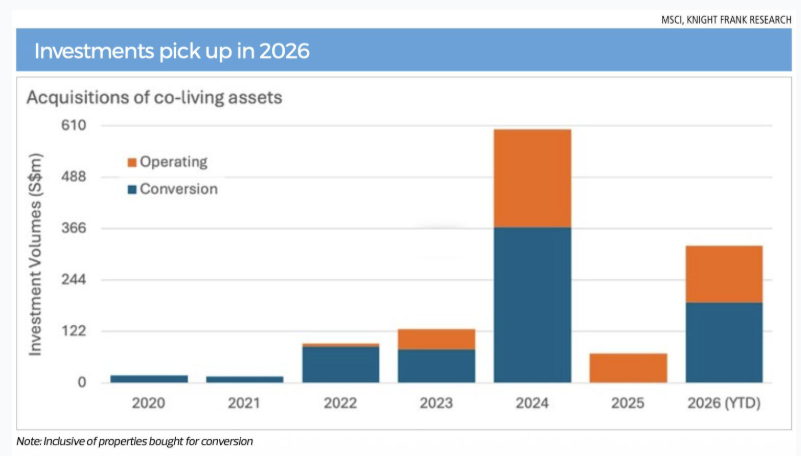
Between 2022 and 2023, URA’s private residential rental index rose sharply, with the increase exceeding 40% at its peak. Direct acquisitions of co-living assets climbed as operators sought to scale their portfolios, while transactions involving operating platforms also emerged, including Mitsubishi Estate’s buyout of Habyt.
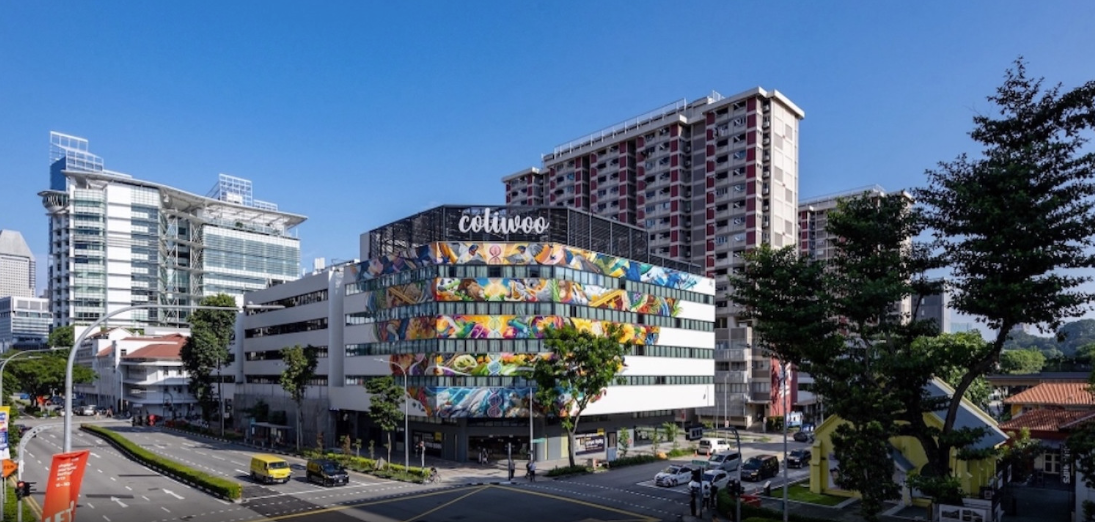
Although deal volumes softened in 2025 amid a tighter supply of investible assets, conversion opportunities have revived activity this year. In August 2026, CapitaLand Ascott Trust’s proposed $134 million acquisition and leaseback of the 212-room Coliwoo Midtown offered a further sign of the sector’s growing institutional appeal.
More reasons to rent
Expectations of a recalibration in co-living demand after the pandemic appear to have been premature.
The sector has continued to expand even as rental market conditions began to normalise, suggesting that demand is being supported by longer-term structural drivers rather than a temporary spurt.
While the surge in rental costs helped improve the economics of the sector, its durability appears to extend beyond that period of exceptional rental growth.
Several factors have expanded demand for flexible housing solutions in Singapore. International student enrolments have continued to grow, while Singapore’s international workforce remains sizeable, with more than 200,000 Employment Pass holders.
The demand base is also broadening beyond the traditional expatriate and student segments. A growing number of local residents are choosing to rent at different life stages, whether while waiting for a new home to be completed, to live closer to their workplaces or to gain greater independence.
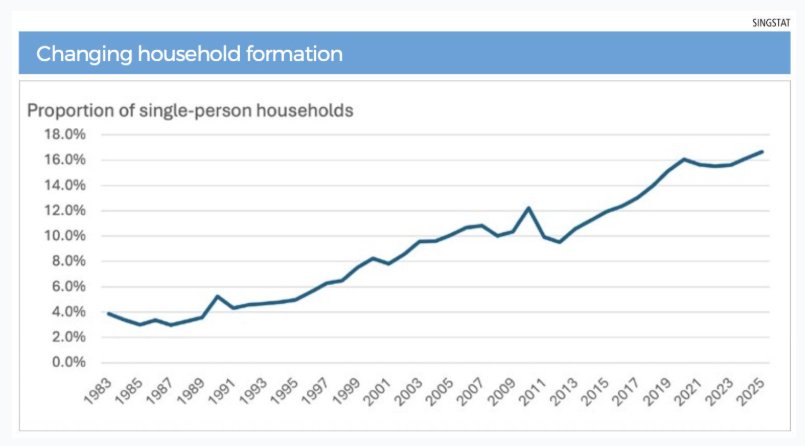
At the same time, household formation patterns have shifted. Single-person households now account for nearly one in six resident households. Notably, much of the increase recorded between 1980 and 2015 has been replicated in just the past decade.
As more people choose to live alone, demand for smaller and more flexible housing options is likely to increase. In this respect, co-living has an advantage: the presence of a community and ready access to amenities can make compact living more appealing.
With the profile of renters becoming more diverse, a rental stock made up predominantly of housing developed for ownership may not always be the optimal solution. An estimated 9,000 to 10,000 co-living keys are now operating across the island, while sustained investment interest points to the segment’s growing presence within Singapore’s housing market.
Living, not just lodging
The growth of co-living points to a broader shift in how housing is being consumed.
Changing lifestyles and the way people live, work and play have contributed to a larger pool of renters. For these groups, location, lease flexibility and ease of move-in can carry significant weight in housing decisions. These preferences align closely with the services typically offered by co-living operators.
Room rentals in co-living properties and private condos with similar attributes are generally competitive.
Headline co-living rents can be higher than conventional room rents, but the difference narrows once furnishings, utilities, connectivity, cleaning services and shorter lease commitments are taken into account. For those with shorter accommodation horizons, avoiding the hassle of setting up their own Wi-Fi and utilities can be a meaningful advantage.
The segment’s appeal also lies in its ability to serve multiple tenant groups through a single platform. Each group may have different housing requirements, but preferences for flexibility, convenience and a professionally managed living environment are widely shared.
This allows operators to tap several sources of demand rather than relying on a single tenant profile.
Co-living is also finding its way into larger mixed-use developments alongside retail, co-working and other lifestyle amenities. From integrated live-work concepts on Orchard Road to resort-style accommodation, the format is being reimagined as a lifestyle offering, not merely a housing solution.
This points to a maturing sector that has moved beyond establishing its viability towards developing more differentiated products with broader appeal.
This shift is also worth considering against the backdrop of recent policy adjustments. At the National Day Rally 2026, Prime Minister Lawrence Wong announced a major reset in public housing, raising the monthly income ceilings for Build-To-Order flats and executive condos to $16,000 and $18,000 respectively, alongside increased ballot priority for young families.
These measures reinforce subsidised homeownership as a central pillar of Singapore’s housing policy, particularly for families.
At the same time, they do not directly address private rental dynamics or the immediate housing needs of singles and households in transition.
This leaves room for market-based rental formats to serve non-traditional, transitional and single-person households. In that sense, institutional co-living can complement, rather than compete with, Singapore’s homeownership model by serving groups whose housing needs may not fit neatly within traditional ownership or rental options.
A broader housing continuum In response to the steep run-up in rents amid tight market conditions, the government has sought to increase rental alternatives.
Aside from higher occupancy caps for larger HDB flats and private residential properties, the introduction of the Serviced Apartments II (SA2) framework in 2023 established a clearer housing format sitting between traditional residential and hospitality uses.
While SA2 is fundamentally a new housing typology and development framework designed for purpose-built rental accommodation, co-living has largely emerged as an operating platform.
Co-living should therefore be viewed as part of a broader housing continuum alongside conventional private rentals.
Many of its tenants are in transitional phases and may eventually gravitate towards housing options that offer greater autonomy, privacy and control over their living environment.
Relative to conventional rentals, higher tenant turnover is inherent in the co-living model. Sustained demand will therefore require a continual replenishment of the tenant base, supported in part by Singapore’s continued appeal as a global city.
Co-living comes of age
What is clear is that the sector has matured and is attracting growing investment interest. A stronger track record of operating performance, an expanding occupier base and policy initiatives such as youth independent-living pilots have strengthened its investment case.
The sector has also demonstrated that growth can be achieved through the repositioning of existing assets. By converting and adapting underutilised buildings, operators have been able to scale in a land-constrained market.
This has broadened the range of opportunities available to investors, from direct asset acquisitions and conversions to the leasing and repositioning of heritage properties.
This is particularly relevant in a higher-interest-rate environment, as co-living offers multiple avenues for value creation, ranging from asset repositioning and adaptive reuse to operational execution.
As the scope for further yield compression narrows, these characteristics are becoming increasingly important drivers of returns.
Underlying these opportunities is a larger and more diversified tenant base, strengthening the sector’s demand fundamentals.
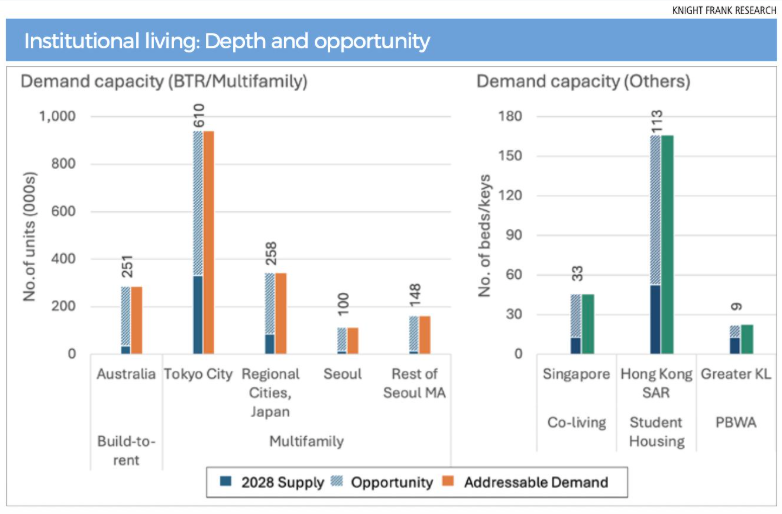
The continued gap between existing supply and addressable demand — the pool of occupiers that could potentially be accommodated by institutional-grade or professionally managed co-living assets — further highlights the scope for expansion.
Based on the size and income profile of key renter groups, Knight Frank’s latest Horizon Research Report, From Niche to Core: Why Asia-Pacific Living Sectors are Entering the Mainstream, estimates that Singapore’s addressable demand for co-living could reach about 45,840 keys by 2028.
Against this, the existing stock of about 9,000 to 10,000 keys is expected to grow by only another 3,000 to 4,000 over the same period. This would leave an estimated supply shortfall of about 32,840 keys by 2028.
This article first appeared in EdgeProp Singapore on 17 September 2026.