Knight Frank Commentary | Q3 2026 Office Report
28 September 2026
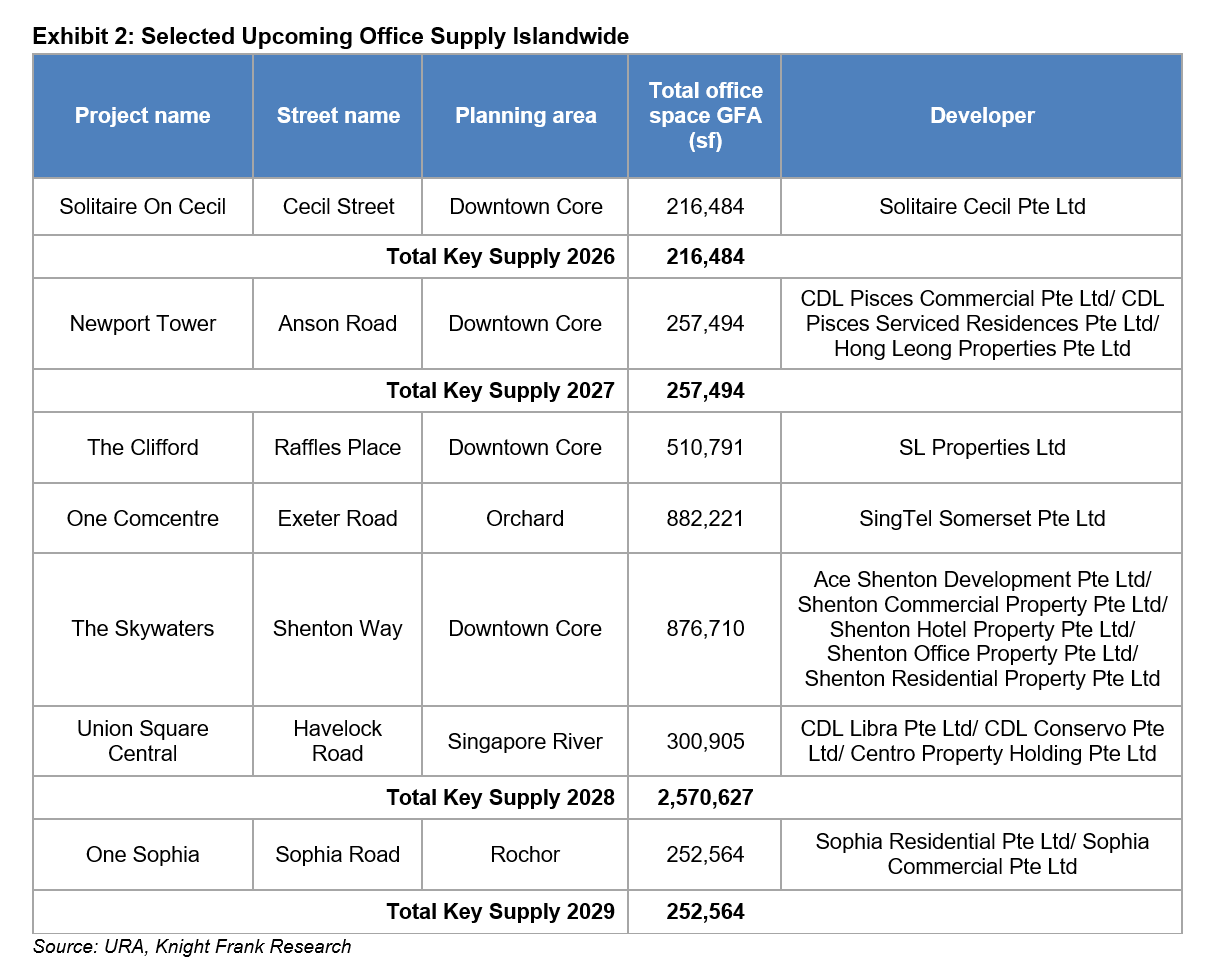
- Estimated CBD New Supply (Q3 2026 - 2030):
3.5 million sf (Gross Floor Area)
- CBD Occupancy: 95.8% (↑ q-o-q)
- Prime Office Rents: S$11.87 psf pm (↑ q-o-q)
Rents and Occupancy
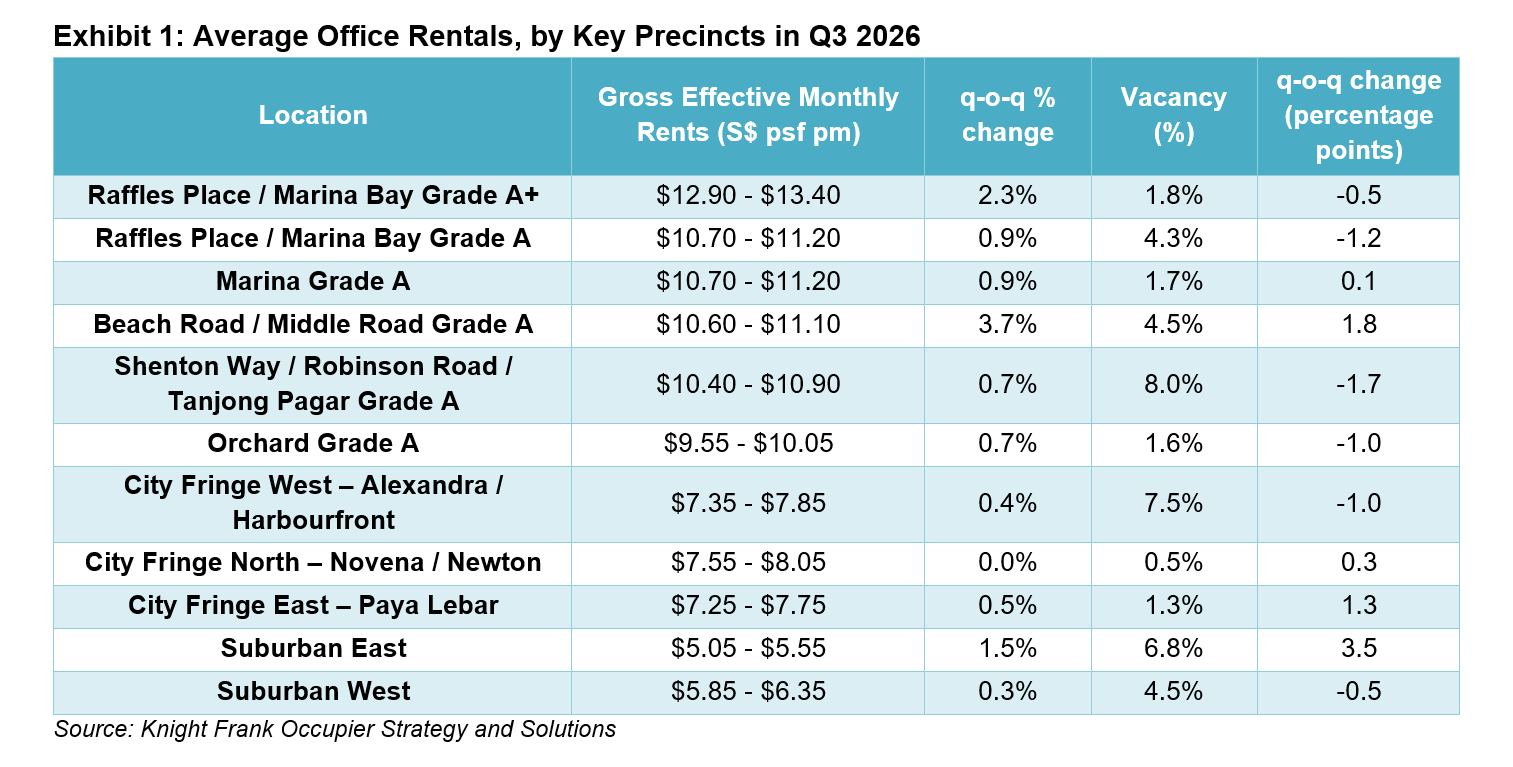
- In Q3 2026, rents of prime grade office space in the Raffles Place / Marina Bay area grew 1.5% q-o-q to record an average of S$11.87 psf pm, supported by strong occupier preference for the limited amount of prime office space in the CBD. Altogether, this reflected a cumulative growth of 3.3% in the nine months from January to September 2026.
- Occupancy levels in the Raffles Place / Marina Bay precinct remained tight in the third quarter of 2026, increasing 0.7 percentage points (pp) to 97.4% from 96.7% in the previous quarter. At the same time, the overall CBD occupancy increased 0.5 pp q-o-q to reach 95.8%. Even though the constrained supply environment limits expansion options for occupiers seeking large contiguous spaces, the continued escalation in occupancy rates underscores the resilient demand for prime office spaces in the CBD.
Demand Drivers
- In Q3 2026, major AI firms continued to announced investment and expansion plans. Databricks will invest more than US$350 million in Singapore and more than double its local headcount over the next three years. Plaud also expanded by doubling its planned investment to S$20 million and establishing its regional headquarters. OpenAI was reported to be negotiating approximately 100,000 sf of office space at Shaw Tower, representing a significant increase from its existing footprint in flexible workspaces. The company also announced plans to establish its first Applied AI Lab outside the United States and hire more than 200 specialised AI professionals. Anthropic was reported to have leased around 100 desks at Ocean Financial Centre through The Executive Centre. Other AI firms including Mistral AI, Sierra and Manus AI also secured dedicated office premises or expanded their presence. In the months and year ahead, more AI-related firms are expected to either move from co-working facilities to establish their own office space or set up shop directly, in a CBD market where quality space options are becoming uncomfortably limited.
- Flexible workspace platforms also continued to grow. According to Knight Frank estimates, as of Q3 2026, there was a total of about 3.9 million sf of co-working spaces in Singapore, and on track to grow at least 2.1% in 2027. This would include JustCo's latest announcement of its 24th Singapore centre at Raffles City Tower comprising approximately 16,000 sf of managed office space to open in January 2027, in addition to the 64,000 sf of office space at JustCo Place in Orchard Point. Given the strong demand, flexible workspace operators continue to scout for available higher-quality and efficient workplaces.
- These twin drivers of the AI revolution and expanding co-working spaces in Singapore’s CBD amid limited prime office supply will inevitably push prime rents further upwards. However, unlike circa 2006/2007 when office rents islandwide were increasing rapidly due to the lack of new builds against surging demand, the rise in rents this time round is largely concentrated among modern prime office buildings in the CBD. Grade B and other older buildings in the CBD, as well as modern facilities such as offices and business park space in the fringe areas have not shown the same level of pressure on occupancy, and rents remain stable. When push-comes-to-shove, some of these other options could provide viable workplace solutions for companies that need to expand.
Economic Sentiment and Outlook
- In the next six to 12 months, corporates would increasingly need to weigh the balance between the scales of a quality CBD office where rents are at a premium with no sign of easing, and the alternative of either an older CBD office with lower specifications and/or a modern facility in the fringe areas where occupational cost is more affordable. It is a pivot between the benefits of branding and talent attraction/retention that typically comes with a shiny CBD office, against business pressures to expand headcount, scale operations and grow as a corporate entity. Unlike other cities in countries where urban sprawl and metropolitan sizes make for prohibitive commuting, Singapore is geographically compact and alternative locations just outside the Central Area can serve as options to mitigate the envisaged rental uplift in the coming months.
- The office market is expected to remain supported by supply conditions in the last quarter of 2026 and into 2027. Availability of prime office spaces remain limited, with the lack of Grade A completions scheduled after Shaw Tower. While this continues to provide landlords with pricing power, particularly in Marina Bay, Raffles Place and other prime CBD submarkets, other options are available as the current rental upswing is not broadbased nor islandwide. Knight Frank expects that prime office rental growth in 2026 will sit at the higher end of the forecast range of 3% to 5% by year-end.