Q3 2026 Investment Report
In today’s pay-to-play market, investors with capital certainty and the ability to execute decisively are best placed to secure quality assets. Amid the uncertain global environment, Singapore’s standing as a preferred destination for long-term real estate investment continues to grow
07 October 2026
TOTAL INVESTMENT SALES
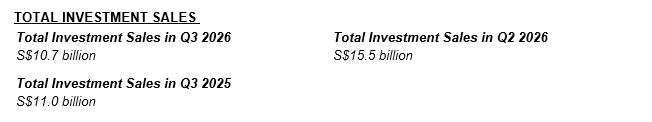
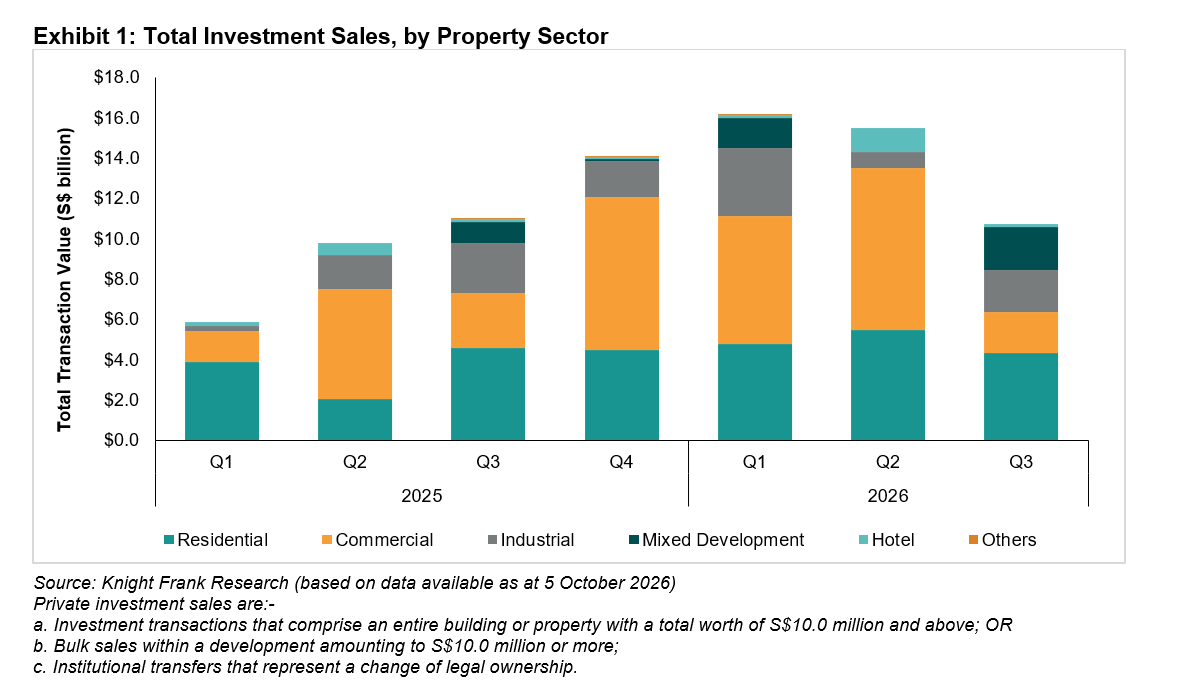
- Singapore’s real estate investment sales moderated to S$10.7 billion in Q3 2026, following the surge in transaction values of S$16.2 billion in Q1 and S$15.5 billion in Q2 (Exhibit 1). Notwithstanding the quarterly decline, investment sales reached S$42.4 billion in the first nine months of 2026, already exceeding the S$40.7 billion recorded in the whole of 2025. Ample liquidity and the current favourable borrowing costs continued to support investor demand, with the use of leverage sustaining acquisition returns. Against this backdrop, investors were prepared to decisively meet competitive pricing in order to secure quality assets, keeping investment activity robust throughout the year.
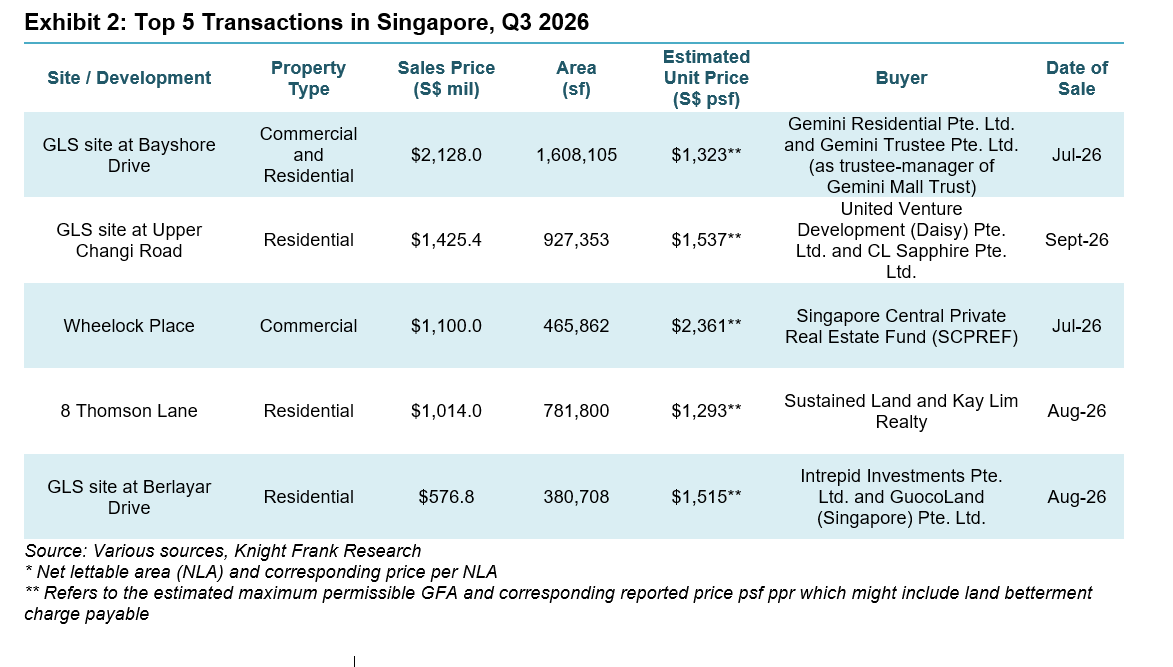
- Residential investment provided the main source of activity in Q3 2026, totalling S$4.3 billion in sales value. Government Land Sales (GLS) continued to account for the bulk of residential investment sales value, with four private residential sites and one commercial and residential site awarded for a combined S$6.5 billion. Separately, the acquisition of 8 Thomson Lane for around S$1.0 billion (including land betterment charges) underscores developers' willingness to pursue private market development site opportunities as they sought to replenish their pipelines.
- In contrast, commercial investment sales eased after the sector led overall transactions in sales value for three consecutive quarters from Q4 2025. Sales totalled S$2.0 billion in Q3 2026, with activity concentrated in two major deals. Singapore Central Private Real Estate Fund (SCPREF), managed by Hongkong Land, acquired Wheelock Place for S$1.1 billion, while Royal Holdings and RB Capital purchased Scotts Square for S$310.0 million. The two transactions underscore continued investor interest in Orchard Road retail-linked commercial assets, supported by shopper traffic, limited new prime retail supply, and the sustained demand in tourism and consumer spending.
- While commercial sales softened, industrial investment activity rebounded. Transaction value more than doubled to S$2.0 billion in Q3 2026. Unlike most previous quarters, when private transactions tended to lead the sector, activity was anchored by several public-sector land sales. Three B2 industrial sites at Jalan Buroh, Kaki Bukit and 5 Tuas Avenue 13 were awarded for S$214.4 million, S$52.8 million and S$43.4 million respectively. Two purpose-built worker dormitory (PBWD) sites at Kranji Close and Lok Yang Way were also awarded for S$343.0 million and S$221.7 million, respectively.
- In the living and hospitality sector, there was a single transaction during the quarter, specifically the acquisition of Coliwoo Midtown by CapitaLand Ascott Trust for S$134.0 million (S$632,075 per key). Nevertheless, there were seven hotel transactions valued at a combined S$1.5 billion recorded in the first nine months of 2026, with total sales value exceeding the nine transactions totalling S$957.2 million for the whole of 2025. The higher investment value points to sustained interest in Singapore’s living sectors.
Collective sales
- In Q3 2026, a freehold residential development comprising six apartments along Upper East Coast Road was successfully sold en bloc for S$14.1 million, reflecting a land rate of S$1,068 psf ppr.
- Looking ahead, the proposed amendments to the collective sales regime could provide some support for the en bloc market, particularly older developments. By lowering the consent thresholds for ageing estates, the changes could make collective sales more attainable and bring a wider pool of redevelopment opportunities to the market. Over time, this may expand the range of residential sites available to developers beyond the GLS programme.
Outbound investment from Singapore
- Data obtained from MSCI Real Assets showed that outbound investment activity rose 31.7% q-o-q to S$16.9 billion in Q3 2026 (Exhibit 3). On a yearly basis, investment value exceeded the S$4.3 billion recorded in Q3 2025, as cross border investment activity remained active.
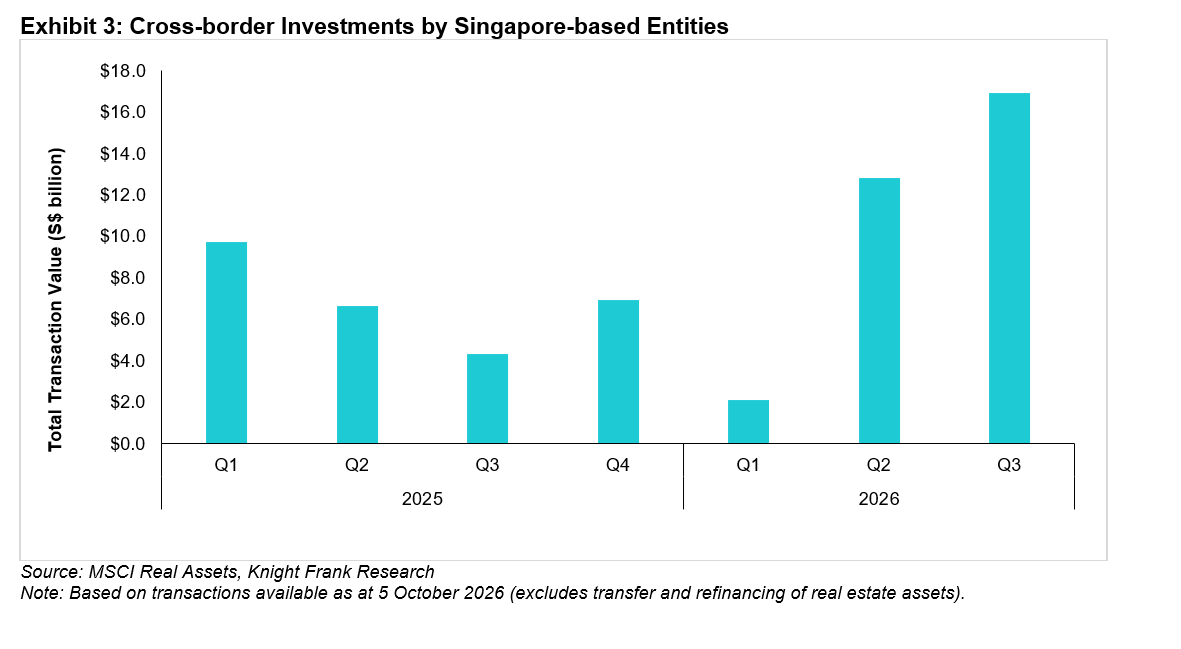
Market outlook
- With real estate investment sales in Singapore totalling S$42.4 billion in the first nine months of 2026, and already surpassing the S$40.7 billion recorded for the whole of 2025, the stage is set for the total in 2026 to achieve a new all-time record. Transaction momentum is expected to remain healthy in the final quarter, with several large ticket deals presently in due diligence. As there are expectations of rate hikes leading to increased borrowing costs, parties involved in ongoing negotiations might be motivated to complete their transactions by year-end.
- Against a persistent backdrop of global economic and geopolitical uncertainty, Singapore has been and continues to remain attractive to domestic and international capital seeking high-quality, income-generating assets in a stabilised modern market at the crossroads of South-east Asian business flows. Taking into account the existing deal pipeline and the potential completion of transactions already under advanced stages of negotiation, Knight Frank projects that total investment sales would reach around the S$50.0 billion mark when all the deals are tallied. This new annual record exceeds the previous peaks of S$40.7 billion in 2025 and the S$35.5 billion recorded in 2017.